Featured
Book Your Free Consultation
Cabin John
Services

First-Time Homebuyer Programs in Cabin John, MD

Few Cabin John homes fit first-time limits: on levy year 2025 bills, 142 of 602 principal residences in ZIP 20818 assessed under $750,000.
★★★★★ Average of 5.0 Stars on Google
The Service

First-time homebuyer assistance: how it works here

First-time homebuyer assistance turns an intimidating process into a guided one: what you can afford, which Montgomery County and Northern Virginia neighborhoods fit, how to structure a first offer, and what happens between contract and keys.

First-time homebuyer programs in Cabin John fit a narrow slice of the housing. On levy year 2025 bills, just 23.6% of owner-occupied homes in ZIP 20818, 142 of 602, carried assessments below $750,000. That’s the slice where state program limits can work. Above it, program rules and prices rarely meet.

The Maryland Mortgage Program sets the ceilings. Montgomery County’s caps sit at $199,320 of income when one or two people share the household, and $232,540 when three or more do. Purchase prices outside targeted areas top out at $1,306,974.

Price limits aren’t the hard part here. Income limits are. A buyer earning enough to carry a Cabin John house often earns too much to qualify, so we check eligibility before touring.

Transfer tax helps. For a buyer purchasing a first Maryland home, the state’s share falls to a 0.25% rate, charged to the seller. On a $700,000 house, that’s $1,750 on the seller’s side of the sheet.

North Bethesda is the comparison many first-time buyers make. Its median owner-home value is $731,800 in 2020-2024 Census estimates, against $1,312,900 in Cabin John. The same budget buys a condo or townhouse there and, if one comes up, a smaller older house here.

Pick the trade-off first.

Patience matters in a small market. With only a few lower-priced homes, a first-time buyer may wait months for the right one. Pre-approval and program paperwork done early let you move the day it lists.

First-time homebuyer assistance lists the programs in general. Monthly cost planning sits on homebuyer budget consultation in Cabin John, and the attached homes have their own page at townhome communities in Cabin John. A county market with lower prices offers wider program use, see First-time homebuyer programs in Gaithersburg. Check eligibility with a Cabin John real estate agent before your first showing.

Where We Work

Cabin John service area

The lower-assessed homes in ZIP 20818 are scattered rather than grouped. Some are attached homes. Others are small original houses on the older streets, some on tight or steep lots that limit expansion. The rebuilt houses and parkway-side homes sit far above program limits. Nearby North Bethesda and the larger county offer more condos and townhouses in range, which is why first-time searches often widen beyond Cabin John. No apartment-style condos exist inside the Census place at all. We map both. Then you choose which trade-off fits.
Neighborhood Coverage

Neighborhoods in Cabin John

Serving every neighborhood across the city. Ask us about yours.

Neighborhood-level guidance comes standard: pricing, timing, and positioning tuned to the block, not just the ZIP code.

Where else to go

Related services and nearby areas

Everything else we publish about this service, this city, and the rest of the DMV.

Answered

Common questions in Cabin John

Q: Can a first purchase happen in Cabin John? A: Sometimes, within a thin slice. Levy year 2025 bills put 142 of 602 owner-occupied Cabin John homes in ZIP 20818 below a $750,000 assessment. That slice can fit Maryland Mortgage Program limits, though income caps often rule out buyers who earn enough to carry the payment. Q: How high can income go under Maryland’s mortgage program here? A: $199,320 if one or two people live in the Montgomery County household. Three or more can earn up to $232,540, and non-targeted purchase prices cap at $1,306,974. Targeted areas get different terms, so we check a Cabin John address against the program’s map with the lender. Q: Does a first-time buyer pay transfer tax in Cabin John? A: Not the state portion. A Cabin John purchase by someone buying a first Maryland home carries a reduced 0.25% state rate, billed to the seller. Under Maryland’s default split, the rest of the transfer and recordation bill shifts to the seller as well.

Sources for these figures

Last reviewed October 10, 2026 by Levi Loveless, licensed in Maryland and Virginia. Every rule, rate and figure on this page links to the source we checked.

  1. Montgomery County Department of Finance, Real Property Taxes 2025 dataset (ZIP 20818 parcels), levy year 2025
  2. Maryland Mortgage Program, June 24, 2026
  3. Md. Code, Tax-Property 13-203
  4. U.S. Census Bureau, ACS 2020-2024 5-year, Table DP04, North Bethesda CDP vs Cabin John CDP, 2020-2024

Check eligibility before you tour.

Share your household size, income range and savings. We’ll test them against current Maryland Mortgage Program limits, list the Cabin John homes in range and show what the same budget buys in North Bethesda, a short drive away.

What does first-time homebuyer assistance cover in Cabin John?

First-time homebuyer assistance means guiding you through every stage of your first purchase in Cabin John. We explain the process, introduce you to lenders who know available state and county programs, and help you search, offer, and close, so the unfamiliar steps feel clear and manageable.

  • Readiness check: We help you understand where you stand before you start touring homes.
  • Lender introductions: We connect you with lenders who can explain loan options and income or credit requirements.
  • Assistance programs: We point you to Maryland and Virginia programs and encourage you to confirm eligibility with the program administrator.
  • Budget planning: We talk through down payment, closing costs, and ongoing ownership expenses.
  • Home search: We focus on homes and neighborhoods that fit your needs and your financing.
  • Offer strategy: We explain how to write an offer that is competitive without stretching beyond your plan.
  • Inspections: We help you understand inspection findings and decide what to request.
  • Closing guidance: We walk you through final documents so settlement day has no surprises.

Can a first purchase happen in Cabin John?

Sometimes, within a thin slice. Levy year 2025 bills put 142 of 602 owner-occupied Cabin John homes in ZIP 20818 below a $750,000 assessment. That slice can fit Maryland Mortgage Program limits, though income caps often rule out buyers who earn enough to carry the payment.

Cabin John at a glance

ServiceFirst-time homebuyer assistance
CityCabin John
CountyMontgomery County, MD
Median home value$1,312,900 (owner-occupied homes, Cabin John CDP, 2020-2024)
AgentLevi Loveless, RE/MAX Realty Group
Licensed inMaryland and Virginia
Office7373 Wisconsin Ave Suite 1700, Bethesda, MD 20814
Phone(301) 275-7744

Source: U.S. Census Bureau, American Community Survey 2020-2024 5-year estimates, table B25077.
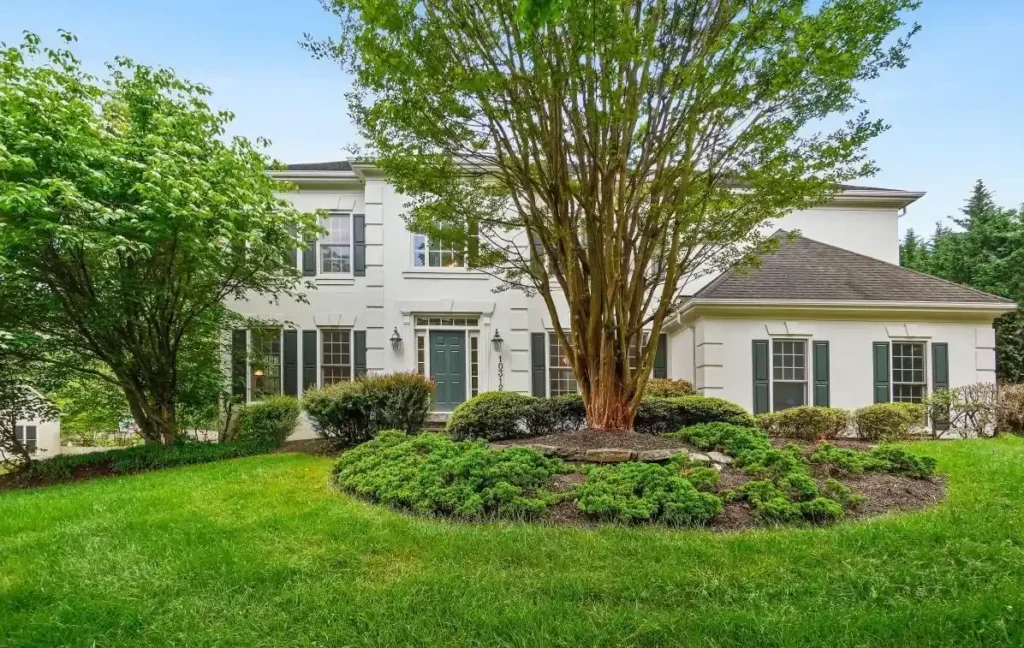
Sold: 10312 Coniston Ct, Potomac, MD

“They were fierce negotiators and worked tirelessly to get me a reduced sales price, which is a testament to their skill and expertise.”

Monica Z., Google review
FAQBefore You Reach Out

Down payment assistance in Cabin John, MD: first-time buyers

Can I use the Maryland Mortgage Program to buy in Cabin John, MD?

You can if the home and your income fit the program's Montgomery County limits, which the official MMP site publishes. Many Cabin John homes sell above those limits, so the program fits mainly lower-priced homes such as some Cabin John Gardens co-op units, if your lender accepts co-op financing.

Does the Montgomery Homeownership Program work in Cabin John, MD?

The Montgomery Homeownership Program, run through the Maryland Mortgage Program, reopened earlier this year and then closed again once its funds were committed. It is not open now. Ask an MMP lender about current programs and watch for any reopening notice.

What is the cheapest way for a first-time buyer to get into Cabin John, MD?

Usually a Cabin John Gardens co-op home or a small older house that needs work. Co-ops trade at lower prices but need board approval and co-op financing, and fixer houses need a repair budget. We compare both with similar homes in nearby Bethesda neighborhoods.

Can I use an FHA loan to buy a house in Cabin John, MD?

Yes, if the home's price fits FHA loan limits and the house passes the FHA appraisal. Older Cabin John cottages may need repairs before an FHA loan will close. Co-op units generally do not work with FHA. A lender can tell you whether FHA or a conventional loan suits you.

Is Cabin John Gardens a good option for first-time buyers in MD?

It can be a lower-priced way into Cabin John, but it is a cooperative: you buy shares, the board approves buyers, and a monthly fee covers shared costs. Fewer lenders finance co-ops. We review the co-op's rules, finances and approval process with you. Call (301) 275-7744 or book a consultation.

Do first-time buyers pay transfer tax in Cabin John, MD?

Qualifying first-time buyers who will live in the home get relief on Maryland transfer taxes, which lowers cash needed at settlement. A co-op purchase is handled differently because shares, not a deed, are transferred. Your settlement company confirms what applies.

PrivateConsultation

Tell us about your move. Levi or Taylor will reply personally, usually the same day.

or call (301) 275-7744