Featured
Book Your Free Consultation
Cabin John
Services

Homebuyer Budget Consultation in Cabin John, MD

Cabin John owners with mortgages pay $4,000 or more monthly at the median in 2020-2024 Census estimates, the survey’s top bracket.
★★★★★ Average of 5.0 Stars on Google
The Service

Home buying consultation: how it works here

A home buying consultation happens before the touring starts and covers what your budget really buys in the current DMV market, whether now is your moment or next spring is, and the sequence (lender, search, offer) that prevents expensive improvisation.

A homebuyer budget consultation in Cabin John starts above the Census ceiling. In 2020-2024 estimates, the median monthly cost for mortgaged owners in the Cabin John census-designated place lands in the survey’s top bracket, $4,000 or more. Countywide the median is $2,929. The table can’t say how far past $4,000 Cabin John goes, so we build the number ourselves.

Tax is the predictable part. The levy year 2026 general rate for unincorporated areas comes to $1.1521 per $100 of value. Applied to a $1.3 million assessment, that’s about $14,977 a year, or roughly $1,248 a month before trash and stormwater charges.

Principal and interest set the rest. Many purchases here need jumbo financing, with its own rate, reserve and down payment rules. A quarter-point on a large loan moves the payment more than most buyers guess.

Association dues apply only to some attached homes. Utility bills run higher on large older houses, especially with oil heat, so we ask the seller for twelve months of bills.

Then add the house. Older roofs, original windows and big wooded lots that need upkeep all belong in the first-year budget.

We build three numbers. One is the payment a lender approves. Another is what you’re comfortable paying. A third is the reserve for repairs.

Comfort beats approval.

Insurance rounds it out. Wooded lots and older roofs can raise premiums, so we get a quote before the offer, not after.

Home buying consultation explains the general session. What each bill line covers is on managing a home purchase in Cabin John, and first-time options are on first-time homebuyer programs in Cabin John. Budgets run lower in a county market with smaller houses, as Homebuyer budget consultation in Germantown shows. Run your numbers past a Cabin John real estate agent before touring.

Where We Work

Cabin John service area

Monthly costs run highest for the rebuilt houses above MacArthur Boulevard, where assessments and loan amounts both climb. Original 1970s houses near the middle of the market cost less to buy but often need roof, window or heating work. The attached homes carry smaller loans and lower tax bills, plus any association dues. Houses on wooded, sloped lots near the canal add tree and drainage upkeep. Each pocket shifts the budget. We price the house you’d actually buy, not an average.
Neighborhood Coverage

Neighborhoods in Cabin John

Serving every neighborhood across the city. Ask us about yours.

Neighborhood-level guidance comes standard: pricing, timing, and positioning tuned to the block, not just the ZIP code.

Where else to go

Related services and nearby areas

Everything else we publish about this service, this city, and the rest of the DMV.

Answered

Common questions in Cabin John

Q: How much do Cabin John homeowners pay each month? A: More than the Census can measure precisely. The 2020-2024 median for mortgaged owners in the Cabin John census-designated place falls in the top bracket, $4,000 or more a month, against $2,929 countywide. A real budget starts from the specific house, its loan and its tax bill. Q: What property tax rate applies to a Cabin John home? A: The levy year 2026 general unincorporated rate of $1.1521 per $100 of assessed value, combining Montgomery County and state rates. On a $1.3 million Cabin John assessment that’s about $14,977 a year. Trash and stormwater charges are billed on top of it. Q: Should a Cabin John budget include repairs? A: Yes, from the first year. Many Cabin John houses are decades old, so roofs, windows and heating systems may be due soon after you move in. We set aside a repair reserve alongside the payment, so a big inspection item doesn’t swallow your savings.

Sources for these figures

Last reviewed October 10, 2026 by Levi Loveless, licensed in Maryland and Virginia. Every rule, rate and figure on this page links to the source we checked.

  1. U.S. Census Bureau, ACS 2020-2024 5-year, Table DP04, Cabin John CDP, 2020-2024
  2. Montgomery County Department of Finance, July 1, 2026
  3. U.S. Census Bureau, ACS 2020-2024 5-year, Table DP04, Cabin John CDP vs Montgomery County, 2020-2024

Find your comfortable payment first.

Bring a recent pay stub, your savings total and a rough down payment figure. We’ll build an approved number, a comfortable number and a repair reserve for a Cabin John house, using real tax and insurance quotes rather than averages.

What does a home buying consultation cover in Cabin John?

A home buying consultation is our first conversation about your goals and how to buy in Cabin John. We explain each step from preparation to closing, discuss neighborhoods and home types, and help you build a search plan, so you can make offers with confidence and avoid common first-time mistakes.

  • Goals and priorities: We separate must-haves from nice-to-haves so your search stays focused.
  • Budget and lender introduction: We explain how pre-approval works and connect you with trusted lenders.
  • Neighborhood fit: We discuss commute, lifestyle, and home styles across Cabin John and nearby areas.
  • The buying process: We outline each stage, from touring to inspection to settlement, in plain language.
  • Making a competitive offer: We cover price, terms, and contingencies so your offer is strong without being reckless.
  • Inspections and due diligence: We explain what inspectors look for and how to respond to findings.
  • Closing costs and paperwork: We help you understand the documents and expenses you will see before settlement.
  • Search setup: We set up listing alerts and a touring plan that matches your schedule.

How much do Cabin John homeowners pay each month?

More than the Census can measure precisely. The 2020-2024 median for mortgaged owners in the Cabin John census-designated place falls in the top bracket, $4,000 or more a month, against $2,929 countywide. A real budget starts from the specific house, its loan and its tax bill.

Cabin John at a glance

ServiceHome buying consultation
CityCabin John
CountyMontgomery County, MD
Median home value$1,312,900 (owner-occupied homes, Cabin John CDP, 2020-2024)
AgentLevi Loveless, RE/MAX Realty Group
Licensed inMaryland and Virginia
Office7373 Wisconsin Ave Suite 1700, Bethesda, MD 20814
Phone(301) 275-7744

Source: U.S. Census Bureau, American Community Survey 2020-2024 5-year estimates, table B25077.
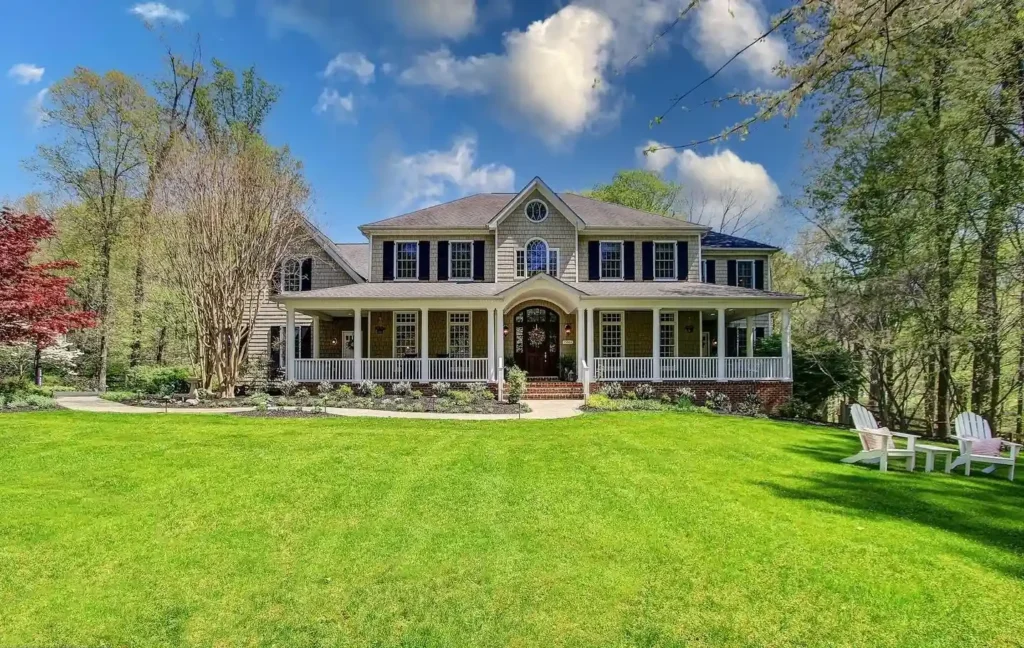
Sold: 15601 Indian Run Ct, Darnestown, MD

“They were fierce negotiators and worked tirelessly to get me a reduced sales price, which is a testament to their skill and expertise.”

Monica Z., Google review
FAQBefore You Reach Out

Home buying budget in Cabin John, MD: costs and down payment

What does the Cabin John Gardens co-op fee include in MD?

A co-op fee usually covers your share of the cooperative's costs, which can include the underlying mortgage, property taxes, insurance, maintenance and reserves. What it covers depends on the co-op, so ask for the current budget and fee breakdown. We review them with you before you make an offer.

How much house can I afford in Cabin John, MD?

Get pre-approved, then build a full monthly budget: mortgage, county property taxes, insurance, utilities and maintenance, plus any co-op fee. Cabin John has few homes for sale, so set your budget before one appears. We help you act quickly when the right home lists.

How much down payment do I need for a house in Cabin John, MD?

It depends on your loan type and price. Many Cabin John homes need a jumbo loan, which often requires a larger down payment than a conforming loan. Mortgage insurance applies to smaller down payments. Your lender can compare options, and we plan offers around them.

Do I need a jumbo loan to buy in Cabin John, MD?

Often, because many Cabin John homes are priced above the conforming loan limit for Montgomery County. Jumbo loans may have stricter credit, reserve and down payment rules. A lender can tell you exactly where the limit falls and which loan fits your purchase.

Who pays transfer and recordation tax when buying in Cabin John, MD?

The contract decides. In Montgomery County, buyer and seller commonly split these taxes, and first-time buyers get a reduced state transfer tax and a county recordation break. Your title company calculates the amounts. We negotiate who pays which as part of your Cabin John offer. Call (301) 275-7744 or book a consultation.

What is the monthly cost of owning a home in Cabin John, MD?

Mortgaged owners in Cabin John pay about $4,000 a month on average, and your figure depends on price, rate, taxes and insurance. Levi Loveless builds your own monthly number for each home, including upkeep, so you compare houses on what they truly cost to own.

Can I buy a home in Cabin John, MD with 10 percent down?

Often yes, though at Cabin John prices a 10 percent down payment may push the loan into jumbo territory, where lender rules differ. We talk with your lender about reserves, rate and mortgage insurance, then show the payment so you can choose the down payment that fits.

How should I set a renovation budget for an older house in Cabin John, MD?

Start with the inspection, then price the systems first: roof, heating and cooling, plumbing, electrical and drainage on a sloped lot. Cosmetic work comes after. Levi Loveless brings contractor input during the inspection period, so the renovation budget shapes your offer.

PrivateConsultation

Tell us about your move. Levi or Taylor will reply personally, usually the same day.

or call (301) 275-7744